How Can I Cancel My Payment and What You Should Know
Canceling a car payment requires knowing your rights, your lender’s policies, and the right steps to follow. Whether you want to stop an auto loan, cancel a car subscription, or reverse a dealer financing charge, this guide covers everything you need. You will learn how to cancel your payment without hurting your credit score or triggering unnecessary fees. Understanding the cancellation process saves you time, money, and stress.
Have you ever found yourself staring at a car payment you no longer want to make? Maybe you returned the vehicle. Maybe you canceled the deal. Or perhaps you simply changed your mind about the whole purchase. Whatever the reason, canceling a car payment can feel confusing and overwhelming. You might wonder if it is even possible. You might worry about fees, credit damage, or getting stuck with charges you did not agree to.
The good news is that canceling a payment is often straightforward if you know the right steps. This guide walks you through everything you need to know about how to cancel my payment in the automotive world. We will cover auto loan cancellations, car lease terminations, dealer payment reversals, and subscription refunds. By the end, you will feel confident and prepared to take action.
Let us be clear about one thing right away. Canceling a payment does not mean ignoring it. Skipping a payment can hurt your credit and lead to collections. What we are talking about here is a legitimate cancellation process that stops future charges and potentially recovers money you have already paid. That is a very different approach, and it works much better for you.
Key Takeaways
- Know Your Rights: Understand the cancellation policy and grace period before taking any action.
- Act Quickly: The sooner you initiate a cancel request, the better your chances of avoiding extra charges.
- Check for Refunds: Many lenders and dealers offer a payment refund if you cancel within the specified window.
- Get Everything in Writing: Always request written confirmation of your cancel request and payment reversal.
- Watch for Cancellation Fees: Some auto finance agreements charge a fee for early termination.
- Monitor Your Credit: Properly canceling a payment protects your credit score from negative impacts.
- Contact Your Lender Directly: The fastest way to cancel is through your lender or service provider.
📑 Table of Contents
- Understanding Why You Might Need to Cancel a Car Payment
- How to Cancel Your Car Payment Step by Step
- Auto Loan Cancellation vs. Early Payoff: What is the Difference?
- Common Mistakes People Make When Trying to Cancel a Payment
- How to Cancel Specific Types of Automotive Payments
- Protecting Yourself During the Cancellation Process
- What Happens to Your Credit When You Cancel a Car Payment?
- Final Thoughts on Canceling Your Car Payment
Understanding Why You Might Need to Cancel a Car Payment
People cancel car payments for many different reasons. Understanding your situation helps you choose the right path forward. Here are the most common scenarios where a cancel car payment request makes sense.
You Returned the Vehicle or Canceled the Sale
Sometimes a car deal falls through after signing the paperwork. Maybe you bought from a dealer and changed your mind during the cooling-off period. Perhaps the vehicle had hidden problems that the seller did not disclose. In these cases, you have a strong basis to cancel the auto finance agreement and request a full or partial refund of your payments.
You Are Ending a Car Subscription Service
Car subscriptions have become very popular in recent years. Companies like Canvas, Fair, and Clutch let you drive a car for a monthly fee. If you decide the subscription is not right for you, you need to know how to cancel your car subscription properly. Most services have specific cancellation procedures and refund policies you must follow.
You Want to Pay Off Your Loan Early
Some drivers want to cancel future payments by paying off their auto loan early. This is different from canceling a payment you already made. Early payoff means you settle the full outstanding balance ahead of schedule. This can save you money on interest and free you from monthly obligations.
You Were Charged in Error
Mistakes happen. A dealer might charge you twice. A lender might process a payment you did not authorize. When this occurs, you need to act fast to get a payment reversal and recover your money. The faster you flag the error, the easier it is to resolve.
How to Cancel Your Car Payment Step by Step
Now let us get into the practical steps. If you want to cancel my payment for an automotive product or service, here is exactly what you should do. Follow these steps carefully to protect yourself and get the best outcome.
Step One: Review Your Contract and Cancellation Policy
Before you do anything else, pull out your contract or agreement. Look for the cancellation policy section. This section tells you your rights as a consumer. It explains how long you have to cancel, whether there are any cancellation fees, and what the refund process looks like.
Pay close attention to the grace period. Many auto finance agreements give you a window of three to seven days to cancel without penalty. Some states offer longer cooling-off periods by law. Knowing your grace period is essential because it determines your options.
Step Two: Contact Your Lender or Dealer Directly
Once you understand your contract, reach out to the right party. If you have an auto loan, contact your lender. If you bought from a dealer, contact the dealer’s finance department. If you have a car subscription, contact the service provider’s customer support team.
Be clear and direct when you make contact. Say something like, “I would like to cancel my payment and terminate the agreement.” Ask them to confirm the process, any fees involved, and the expected timeline for a refund. Always keep records of every conversation, including dates and names of representatives.
Step Three: Submit Your Cancel Request in Writing
Verbal requests are helpful, but they are not enough on their own. Always follow up with a written cancel request. Send an email or certified letter that clearly states your intention to cancel. Include your account number, the date of the request, and any relevant details about the transaction.
A written request creates a paper trail. If any disputes arise later, you have proof that you acted in good faith and within the proper timeframe. This is one of the most important steps many people skip, and it can cost them dearly.
Step Four: Confirm the Refund Amount and Timeline
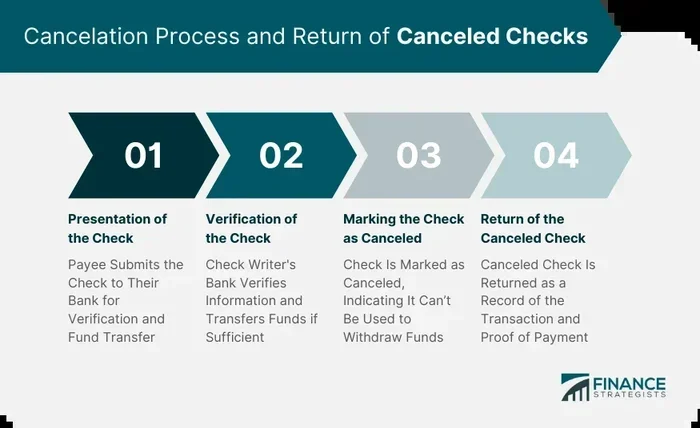
After your cancel request is processed, ask for confirmation of the refund amount and the expected refund timeline. Most lenders process refunds within five to fifteen business days. Some may take longer, especially if the payment was made through a third-party processor.
Make sure you understand whether you will receive a full refund or a partial one. Some agreements deduct a cancellation fee or charge a restocking fee. Knowing this upfront prevents surprises and helps you plan accordingly.
Step Five: Monitor Your Account and Credit Report
Once your cancel request is submitted, do not just sit back and wait. Monitor your bank account to confirm the refund arrives. Check your credit report to make sure the account shows as closed or paid off. If you notice any errors, dispute them immediately with the credit bureau and your lender.
Keeping an eye on your account after cancellation protects you from unauthorized charges and ensures everything is handled correctly. It is a simple habit that pays off in the long run.
Auto Loan Cancellation vs. Early Payoff: What is the Difference?
Many people confuse canceling a car payment with paying off a loan early. These are two very different processes, and understanding the distinction matters.
What Is Auto Loan Cancellation?
Auto loan cancellation means you are terminating the entire agreement. This usually happens when a deal is voided, a vehicle is returned, or you are within a legal cooling-off period. The goal is to undo the transaction entirely and get your money back.
What Is Early Loan Payoff?
Early loan payoff means you are paying off the remaining balance before the scheduled end date. You are not canceling the loan. You are finishing it ahead of schedule. This is a smart financial move that reduces your total interest cost and frees up your monthly budget.
Here is a quick comparison to help you understand the differences:
| Aspect | Loan Cancellation | Early Payoff |
|---|---|---|
| Purpose | Terminate the agreement entirely | Pay off remaining balance early |
| Refund Possible? | Yes, usually partial or full | No, but you save on interest |
| Credit Impact | Neutral if handled properly | Positive, shows responsible payment history |
| Timing | Must act within grace period or legal window | Can be done at any time |
| Fees | May have cancellation fees | May have early payoff fees |
Both options have their place. The right choice depends on your situation. If you no longer want the vehicle or the deal fell through, cancellation is the way to go. If you simply want to be done paying sooner, early payoff is the better route.
Common Mistakes People Make When Trying to Cancel a Payment
Avoiding mistakes can save you a lot of trouble. Here are the most common errors people make when they try to cancel their payment and how to steer clear of them.
Missing the Grace Period
The biggest mistake is waiting too long. Most cancellation policies have a strict time limit. If you miss the window, you may lose your right to a full refund. Set a calendar reminder as soon as you sign any agreement, and act quickly if you decide to cancel.
Skipping the Written Request
As we mentioned earlier, verbal requests are not enough. Many people call their lender, feel reassured, and then do nothing else. Without a written record, the lender has no obligation to honor your request. Always follow up in writing.
Ignoring Cancellation Fees
Not every cancellation is free. Some auto finance agreements include early termination fees that can be substantial. Read the fine print before you cancel so there are no surprises. If a fee seems unreasonable, you can negotiate with your lender or seek legal advice.
Stopping Payments Without Notice
Do not simply stop making payments because you want to cancel. This is one of the worst things you can do. Missed payments lead to late fees, credit damage, and potential collections. Always go through the proper cancellation process before you stop paying.
Not Checking for Refunds
After canceling, many people forget to verify that the refund actually arrived. Always confirm the refund in your bank account. If it does not appear within the stated timeline, follow up immediately with your lender or dealer.
How to Cancel Specific Types of Automotive Payments
The automotive world includes many different types of payment arrangements. Each one has its own cancellation process. Here is a closer look at how to handle the most common scenarios.
Canceling a Car Lease Payment
If you have a car lease and want to stop making payments, you have a few options. You can return the vehicle early, but this usually comes with a lease termination fee. Some leases allow you to transfer the lease to another person, which can help you avoid penalties. Check your lease agreement for the specific lease termination terms and conditions.
Canceling an Extended Warranty Payment
Extended warranties are common add-ons at car dealerships. If you decide you do not want the warranty, you can often cancel the warranty payment within a certain period. Most states require dealers to offer a cooling-off period for extended warranties. Contact the warranty provider directly to initiate the cancel request and ask about your refund eligibility.
Canceling a Car Subscription Payment
Car subscriptions are monthly services that give you access to a vehicle. Canceling a subscription is usually simpler than canceling a loan. Most subscription services let you cancel through their app or website. Look for the cancel button in your account settings, and follow the prompts. Always confirm the cancellation in writing and check for any outstanding balance you may owe.
Canceling a Roadside Assistance Membership Payment
If you pay for roadside assistance through your dealer or a third-party provider, you can usually cancel the membership at any time. Check your membership agreement for the cancellation procedure. Some providers offer a payment refund for unused months if you cancel early. Call the customer service number on your membership card to start the process.
Protecting Yourself During the Cancellation Process
Canceling a payment should not leave you vulnerable. Here are some expert tips to keep yourself safe and informed throughout the process.
Keep Copies of Everything
Save every email, letter, and confirmation related to your cancel request. Create a folder on your computer or in your email where you store all cancellation documents. If you ever need to dispute a charge or prove you followed the proper process, these records will be invaluable.
Know Your State Laws
Consumer protection laws vary by state. Some states offer stronger protections for car buyers than others. For example, California has a two-day cooling-off period for certain auto purchases. New York offers similar protections for dealership transactions. Research your state’s specific laws to understand what rights you have.
Do Not Feel Pressured
Dealers and lenders may try to pressure you into keeping the agreement. They might tell you canceling is difficult or that you will face serious consequences. Stand firm. You have legal rights, and a reputable company will respect your decision to cancel my payment. If they do not, you can file a complaint with your state’s consumer protection agency.
Consider Consulting a Professional
If your cancellation involves a large amount of money or a complex agreement, it may be worth consulting an attorney or a consumer advocacy organization. Many legal aid services offer free consultations. A professional can review your contract and advise you on the best course of action.
What Happens to Your Credit When You Cancel a Car Payment?
One of the biggest concerns people have is how cancellation affects their credit score. The answer depends on how you handle the process.
If you cancel properly and follow the correct procedures, your credit score should not suffer. The account will simply show as closed or settled. However, if you stop making payments without canceling, the missed payments will be reported to credit bureaus. This can significantly damage your credit score and make it harder to get approved for future loans.
Here are a few tips to protect your credit during the cancellation process:
- Always get written confirmation of your cancel request.
- Ensure the lender reports the account as closed or paid.
- Check your credit report within 30 days of cancellation.
- Dispute any errors or inaccurate information immediately.
- Avoid closing old credit accounts unnecessarily, as this can lower your credit score.
Taking these steps ensures that canceling a payment does not create long-term financial problems. Your credit health matters, and a little extra effort goes a long way.
Final Thoughts on Canceling Your Car Payment
Canceling a car payment does not have to be a stressful experience. When you know your rights, follow the proper steps, and act quickly, you can protect your finances and get the outcome you need. Whether you are canceling an auto loan, a car lease, a subscription, or an extended warranty, the process is manageable if you approach it the right way.
Remember to review your contract carefully, submit your cancel request in writing, confirm the refund details, and monitor your account afterward. These simple steps make a huge difference. They keep you informed, protect your credit, and ensure you get any money you are entitled to back.
The automotive industry can feel overwhelming, especially when payments and contracts are involved. But knowledge is your best tool. Now that you understand how to cancel my payment and what to watch out for, you are in a much stronger position. Take action confidently, and do not let uncertainty hold you back from making the best financial decision for your situation.
Frequently Asked Questions
Can I cancel a car payment after I have already made it?
Yes, in many cases you can cancel a payment you have already made, especially if you are within the grace period or cooling-off window outlined in your contract. Contact your lender or dealer immediately and submit a written cancel request to start the refund process.
How long does it take to get a refund after canceling a car payment?
Most refunds are processed within five to fifteen business days. However, the timeline can vary depending on your lender, the payment method used, and whether any third-party processors are involved. Always confirm the expected timeline when you submit your cancel request.
Will canceling a car payment hurt my credit score?
Not if you handle it properly. Following the correct cancellation process and ensuring the account is reported as closed or settled protects your credit score. The real risk to your credit comes from stopping payments without canceling, which leads to missed payments and negative credit reporting.
Are there fees for canceling a car loan early?
Some auto finance agreements include early termination or cancellation fees. These fees vary by lender and state law. Always read your contract carefully before canceling, and ask your lender to explain any fees upfront so there are no surprises.
What is the difference between canceling a car loan and paying it off early?
Canceling a car loan means terminating the agreement entirely and getting a refund of payments made, usually within a grace period. Paying off a loan early means settling the remaining balance ahead of schedule without canceling the contract. The two processes have different goals and outcomes.
Can I cancel a car subscription at any time?
Most car subscription services allow you to cancel at any time, but the terms vary by provider. Some require a notice period of 30 days or more, and others may charge a fee for early cancellation. Always check the subscription agreement and confirm the cancel process in writing before you stop paying.