Are Tacomas Expensive to Insure Here is What to Expect
Are Tacomas expensive to insure? The answer depends on several factors including your location, driving history, and the specific Tacoma trim you own. Toyota Tacoma insurance rates are generally moderate compared to other midsize trucks, but certain factors can push premiums higher. Understanding what drives the cost of Tacoma insurance helps you make informed decisions and potentially save hundreds of dollars each year.
Are Tacomas expensive to insure? This is a question that many truck buyers ask before pulling the trigger on a Toyota Tacoma. The short answer is that Tacoma insurance costs fall somewhere in the middle of the pack for midsize trucks. But the longer answer involves several moving parts that can make your premium either affordable or surprisingly steep.
If you are thinking about buying a Tacoma or already own one, understanding what goes into your insurance rate is essential. Insurance companies look at many factors when setting your price. Some you can control. Others you cannot. This guide breaks down everything you need to know about Toyota Tacoma insurance so you can make smart choices and avoid surprises.
The Toyota Tacoma has been one of the most popular midsize trucks on the road for years. Its reliability, resale value, and off-road capability make it a standout. But popularity also means insurance companies pay close attention to this model. Let us walk through what affects Tacoma insurance rates and how you can manage your costs effectively.
Key Takeaways
- Tacoma insurance costs vary widely based on your location, driving record, and chosen coverage levels.
- Newer Tacoma models cost more to insure due to higher replacement value and advanced features.
- Safety features like Toyota Safety Sense can qualify you for meaningful insurance discounts.
- Comparing quotes from multiple insurers is the single best way to find affordable Tacoma coverage.
- Your deductible choice directly impacts your monthly or annual premium amount.
- Maintaining a clean driving record keeps your Tacoma insurance rates as low as possible.
- Understanding coverage types helps you avoid paying for unnecessary extras.
📑 Table of Contents
Understanding Tacoma Insurance Costs
What Makes Up Your Insurance Premium
Your insurance premium is the amount you pay for coverage. It can be billed monthly, every six months, or annually. Several components make up this cost. Liability coverage pays for damage you cause to others. Collision coverage covers damage to your Tacoma after an accident. Comprehensive coverage handles non-accident damage like theft or weather events.
Beyond these core coverages, you may also pay for uninsured motorist protection, medical payments, and roadside assistance. Each add-on increases your total premium. The key is finding the right balance between protection and affordability. Not every driver needs every type of coverage.
The average annual insurance cost for a Toyota Tacoma ranges from about $1,400 to $2,000. This is based on full coverage policies for a standard trim. Rates can be lower for basic liability-only policies and higher for premium packages. Your personal situation will determine where you fall in that range.
How Insurance Companies Classify the Tacoma
Insurance companies group vehicles into categories called insurance groups or tiers. The Tacoma typically falls into a moderate-to-high group. This is because it is a truck, and trucks generally cost more to repair than sedans. The Tacoma also has a strong resale value, which means replacement parts and full vehicle claims cost insurers more.
However, the Tacoma is not in the highest insurance group. It is not as expensive to insure as some full-size trucks or luxury vehicles. Compared to a Ford F-150 or a Ram 1500, the midsize Tacoma often sits at a similar or slightly lower insurance tier. This makes it a reasonable choice for budget-conscious truck buyers.
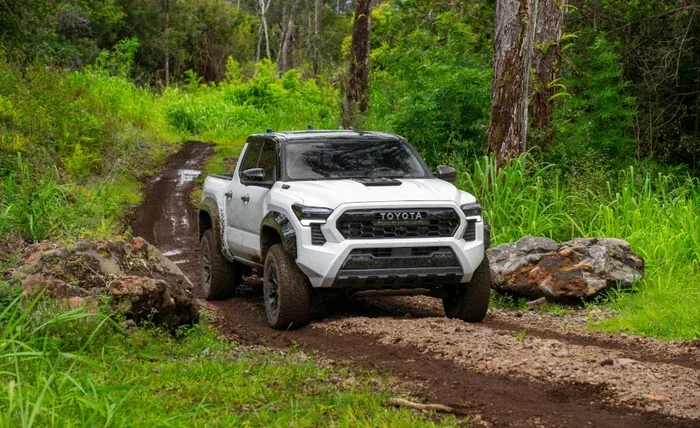
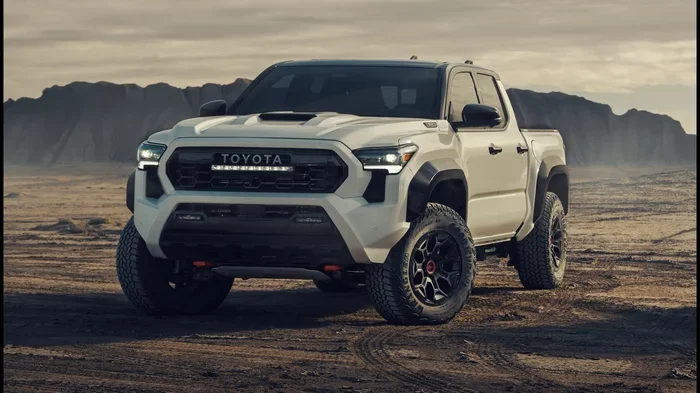
When you are shopping for a Tacoma, consider how the trim level affects insurance. A base SR trim will usually cost less to insure than a TRD Pro or Limited. Higher trims have more expensive parts and advanced features that increase the risk for insurers. Keep this in mind as you compare options.
Factors That Affect Tacoma Insurance Rates
Your Location Matters
Where you live has a huge impact on your insurance rate. If you park your Tacoma on the street in a busy city with high crime rates, expect to pay more. Insurance companies factor in theft risk, vandalism rates, and accident frequency for your specific area.
Rural drivers often pay less for Tacoma insurance. There are fewer accidents and less theft in rural areas. Urban drivers in cities like Los Angeles or New York will see higher premiums. Even within the same state, rates can vary dramatically from one zip code to the next.
Weather also plays a role. If you live in an area prone to hail, flooding, or hurricanes, your comprehensive coverage premium will likely be higher. Insurance companies assess regional risk carefully when setting your price.
Your Driving History and Profile
Your personal driving record is one of the biggest factors insurers consider. A clean record with no accidents or violations will get you the best rates. Even a single speeding ticket can increase your premium by 20 to 30 percent. Multiple violations can make Tacoma insurance much more expensive.
Your age and gender also play a role. Younger drivers, especially those under 25, pay significantly more. This is because statistics show they are more likely to be involved in accidents. Married drivers and those over 30 typically see lower rates. Your annual mileage matters too. If you drive your Tacoma less, you may qualify for low-mileage discounts.
Your credit score can also influence your insurance rate in many states. Insurers use credit-based insurance scores to predict claim likelihood. Maintaining good credit helps keep your premiums down. This is one reason why keeping your finances in order matters beyond just your bank account.
Coverage Levels and Deductibles
The amount of coverage you choose directly affects your premium. Higher coverage limits mean higher premiums. A $100,000 bodily injury liability limit will cost more than a $50,000 limit. Similarly, lowering your deductible reduces your out-of-pocket cost after a claim but increases your regular premium.
Many drivers choose a $500 deductible for collision and comprehensive coverage. This is a good middle ground. If you want lower monthly payments, you can opt for a $1,000 deductible. Just make sure you can afford to pay that amount if you file a claim.
It is also worth noting that if you have a loan or lease on your Tacoma, your lender will require full coverage. This includes both collision and comprehensive. Once the loan is paid off, you can adjust your coverage and potentially lower your rate.
How to Lower Your Tacoma Insurance Premium
Shop Around and Compare Quotes
The single most effective way to save on Tacoma insurance is to compare quotes from multiple companies. Every insurer uses its own formula to set rates. What costs $1,800 per year with one company might cost $1,200 with another. Shopping takes only a few minutes and can save you hundreds.
Use online comparison tools to get quotes quickly. Call at least three or four insurers directly. Do not just go with your current provider or the first quote you receive. Insurance rates change frequently, so reviewing your policy annually is a smart habit.
Also consider working with an independent insurance agent. They can compare rates across many companies for you at no extra cost. This takes the guesswork out of finding the best deal for your Tacoma.
Take Advantage of Discounts
Most insurers offer discounts that can significantly reduce your premium. Safe driver discounts are the most common. If you have no accidents or violations for three to five years, you qualify. Some companies also offer defensive driving course discounts.
bundling discounts are another great way to save. If you have homeowners or renters insurance with the same company, you can often get a 10 to 20 percent discount on your auto policy. Multi-car discounts also apply if you insure more than one vehicle.
The Tacoma comes with several safety features that may qualify for additional discounts. Anti-lock brakes, stability control, airbags, and advanced driver-assistance systems are all valued by insurers. If your Tacoma has Toyota Safety Sense, make sure to tell your agent. These features can lead to meaningful savings on your vehicle insurance.
Maintain Continuous Coverage
Never let your insurance lapse. Even a short gap in coverage can cause your rates to spike when you reinstate. Insurers view lapses as a red flag. They assume you are a higher-risk driver and adjust your premium accordingly.
Set up automatic payments to ensure your policy never cancels. If you are struggling to afford your current rate, talk to your agent before canceling. They may be able to adjust your coverage or suggest alternatives. Keeping your Tacoma insured at all times protects both your wallet and your driving record.
Improve Your Credit Score
In states where credit-based insurance scores are used, improving your credit can lower your rates. Pay your bills on time, reduce your debt, and check your credit report for errors. Even a small credit score improvement can translate into meaningful premium savings.
This is a long-term strategy, but it pays off. Many drivers see their insurance rates drop as their credit improves over time. It is one of the less obvious benefits of maintaining good financial health.
Tacoma Insurance vs Other Midsize Trucks
How the Tacoma Compares
When you are shopping for a truck, it helps to compare insurance costs across models. The Tacoma generally sits in a moderate insurance cost range. Here is a quick comparison of how the Tacoma stacks up against similar midsize trucks.
| Truck Model | Average Annual Premium | Insurance Group Tier |
|---|---|---|
| Toyota Tacoma | $1,400 – $2,000 | Moderate |
| Chevrolet Colorado | $1,500 – $2,100 | Moderate-High |
| Honda Ridgeline | $1,300 – $1,900 | Moderate |
| Ford Ranger | $1,450 – $2,050 | Moderate |
| Nissan Frontier | $1,350 – $1,950 | Moderate-Low |
As you can see, the Tacoma is competitive with its rivals. The Honda Ridgeline tends to be slightly cheaper to insure, partly because it is based on a car platform. The Colorado and Ranger are in a similar range. None of these trucks will break the bank when it comes to insurance.
Why the Tacoma Holds Its Value
One unique thing about the Tacoma is its resale value. Tacomas hold their value incredibly well, often better than almost any other truck. This is great for your wallet when selling, but it affects insurance. A high-value vehicle costs more to replace, which means higher premiums.
If you know the value of your Tacoma, you can make smart coverage decisions. For older Tacomas, you might consider dropping comprehensive and collision coverage if the vehicle is worth less than your deductible. For newer models, keeping full coverage is usually the right move.
Knowing how much your Tacoma is worth helps you avoid overpaying for insurance. You can also use this information when deciding whether to repair or total a damaged vehicle. Understanding vehicle value is a key part of managing insurance costs effectively.
Common Mistakes That Increase Tacoma Insurance Costs
Skipping Coverage to Save Money
Some drivers drop coverage to lower their premium. This is a risky move. If you cause an accident without liability insurance, you are personally responsible for all damages. Medical bills, vehicle repairs, and legal fees can quickly add up to tens of thousands of dollars.
In the worst case scenario, an at-fault accident without adequate coverage can put your assets at risk. Your savings, investments, and even your home could be in jeopardy. Always maintain at least the minimum required liability coverage in your state, and consider higher limits for better protection.
Not Updating Your Policy
Life changes affect your insurance needs. If you move, get married, or buy a new Tacoma trim, your rates may change. Failing to update your policy means you could be paying too much or not have enough coverage when you need it most.
Review your policy at least once a year. Update your information with your insurer. Ask about new discounts you may qualify for. These small steps can make a big difference in what you pay for Tacoma insurance.
Choosing the Wrong Deductible
A deductible that is too low means high monthly premiums. A deductible that is too high means you cannot afford to pay it after a claim. Most financial experts recommend a $500 deductible for most drivers. This balances affordability with out-of-pocket risk.
If you have significant savings, a $1,000 deductible might work well. It lowers your premium noticeably. But make sure you actually have that money available if you need it. Insurance is about managing risk, not eliminating it entirely.
Expert Tips for Tacoma Owners
Insurance experts recommend several strategies for keeping Tacoma insurance costs manageable. First, always ask about every available discount. You might be eligible for discounts you did not even know about. Loyalty discounts, affinity group discounts, and employer-based discounts can all add up.
Second, consider usage-based insurance programs. Many major insurers now offer telematics programs that track your driving habits. Safe drivers can earn significant discounts. If you drive your Tacoma carefully and avoid hard braking or speeding, you could save 10 to 30 percent on your premium.
Third, pay your premium in full when possible. Many insurers charge a fee for monthly payments. Paying annually or semi-annually avoids these fees and can save you money over time. It is a small change that adds up.
Finally, do not assume all insurers treat the Tacoma the same way. Some companies specialize in truck insurance and understand the vehicle better than others. They may offer more competitive rates or better coverage options specifically tailored to truck owners.
Conclusion
Are Tacomas expensive to insure? The answer is nuanced. Tacomas are not the cheapest vehicles to insure, but they are far from the most expensive either. Their moderate insurance group placement, strong safety features, and widespread popularity keep rates reasonable for most drivers.
Your personal situation plays the biggest role in determining your final premium. Where you live, your driving history, your coverage choices, and your deductible all matter. By shopping around, taking advantage of discounts, and maintaining good coverage habits, you can keep your Tacoma insurance costs under control.
The Toyota Tacoma is a fantastic truck that offers years of reliable service. Protecting that investment with the right insurance policy is one of the smartest things you can do. Take the time to understand your options, compare quotes, and choose a policy that fits both your needs and your budget. Your wallet will thank you for it.
Frequently Asked Questions
Why are Tacoma insurance rates so high?
Tacoma insurance rates can be higher than average because the truck holds its value well and repair costs are above those of passenger cars. Insurance companies also classify the Tacoma as a midsize truck, which carries more risk than a sedan. Your location, driving history, and coverage choices all influence your specific rate.
Does the Tacoma TRD trim cost more to insure?
Yes, higher trims like the TRD Pro or Limited typically cost more to insure. These versions have more expensive parts, advanced features, and higher overall vehicle values. Insurers factor in the cost of repairs and replacement when setting your premium for upgraded trims.
How can I lower my Tacoma insurance premium?
You can lower your premium by shopping around for quotes, bundling your auto policy with homeowners insurance, maintaining a clean driving record, and taking advantage of safety feature discounts. Increasing your deductible and reducing coverage on older vehicles are also effective strategies.
Is full coverage required for a Toyota Tacoma?
Full coverage is not legally required in most states, but lenders and leasing companies typically mandate it if you have a loan or lease on your Tacoma. Full coverage includes both collision and comprehensive, protecting you from a wide range of financial risks beyond basic liability.
Does the Tacoma safety rating affect insurance?
Yes, the Tacoma has strong safety ratings and advanced safety features that can positively impact your insurance rate. Vehicles with good crash test scores and active safety systems like Toyota Safety Sense often qualify for lower premiums and additional discounts from many insurers.
Are older Tacomas cheaper to insure?
Generally yes, older Tacomas cost less to insure because they have lower market values. This means the cost of a claim or total loss is lower for the insurance company. However, you should still maintain adequate coverage, especially if the vehicle still has significant value or you have a loan on it.