Find Out If You Can Prequalify for Toyota Financing
You can prequalify for Toyota financing online, over the phone, or at your local dealer. Prequalification gives you a quick look at the loan terms and interest rates you may qualify for before you even step foot on the lot. This process is fast, free, and has no impact on your credit score. Knowing your options ahead of time puts you in a strong position when negotiating with the dealer.
Have you ever wondered if you can prequalify for Toyota financing before you even start shopping for a new or used Toyota? The answer is yes, and it is one of the smartest moves you can make before walking onto a lot. Prequalification gives you a clear picture of what kind of loan or lease you might qualify for. It saves you time, reduces surprises, and puts you in the driver seat when it comes to negotiations.
Toyota financing has become more accessible than ever. Whether you have excellent credit or you are working to rebuild it, there are options available to you. In this guide, we will walk you through everything you need to know about prequalifying for Toyota financing. We will cover how the process works, what requirements you need to meet, and tips to get the best deal possible.
By the end of this article, you will have a solid understanding of the Toyota prequalification process. You will know exactly what to expect and how to prepare. Let us dive in and help you get one step closer to driving home in your dream Toyota.
Key Takeaways
- Easy Online Process: You can prequalify for Toyota financing from home in just a few minutes using the Toyota website or your dealer’s portal.
- No Credit Score Impact: Prequalification typically uses a soft credit check, so your score stays safe.
- Know Your Budget First: Getting prequalified helps you understand what you can afford before shopping.
- Multiple Financing Options: Toyota offers several financing paths including loans, leases, and special programs.
- Dealer Negotiation Power: Walking in prequalified gives you leverage when discussing terms.
- Bad Credit Options Exist: Even with lower credit scores, there are paths to Toyota financing approval.
📑 Table of Contents
- What Is Toyota Prequalification?
- How to Prequalify for Toyota Financing
- Toyota Financing Requirements
- Toyota Financing Options Available
- Tips to Get the Best Toyota Financing Deal
- Common Mistakes to Avoid When Prequalifying for Toyota Financing
- Expert Insights on Toyota Financing
- Frequently Asked Questions About Toyota Prequalification
- Conclusion
What Is Toyota Prequalification?
Toyota prequalification is a preliminary check that gives you an estimate of the financing terms you may qualify for. Think of it as a quick snapshot of your borrowing potential. It is not a final approval, but it is a very useful starting point.
When you prequalify, you typically provide some basic financial information. This includes your income, employment status, and a general idea of your credit health. The lender or Toyota Financial Services then reviews this information and offers you a ballpark range of loan amounts, interest rates, and monthly payments.
How Prequalification Differs from Preapproval
People often use these two terms interchangeably, but they are not the same thing. Prequalification is a rough estimate based on information you provide yourself. Preapproval is a more formal process that involves a hard credit check and a deeper review of your finances.
Prequalification is faster and less invasive. Preapproval gives you a stronger position because the lender has done the heavy lifting. Many buyers use both steps together for the best results.
Why Prequalification Matters
Prequalification matters because it sets realistic expectations. You will not waste time looking at Toyotas that are outside your budget. It also helps you avoid the pressure that can come from walking onto a lot without any idea of what you can afford.
When you show up prequalified, dealers take you more seriously. You are not just browsing. You are a serious buyer with a plan. This gives you an edge during negotiations.
How to Prequalify for Toyota Financing
The prequalification process is straightforward and convenient. You have multiple ways to get started, and most of them take less than 15 minutes. Let us break down each option so you can choose the one that works best for you.
Option 1: Prequalify Online Through Toyota
The easiest way to prequalify is through the official Toyota website. Toyota Financial Services offers an online prequalification tool that lets you enter your basic details from the comfort of your home. You will need to provide information like your name, address, income, and employment details.
The online tool runs a soft credit inquiry, which means it does not hurt your credit score. Within minutes, you will receive an estimate of the financing options available to you. You can also explore Toyota lease options and compare them against loan terms right on the same page.
One great thing about the online process is that you can save your results and bring them to the dealer. This shows the salesperson that you have done your homework and you are ready to move forward.
Option 2: Prequalify Over the Phone
If you prefer talking to a person, you can call Toyota Financial Services directly. A representative will walk you through the prequalification process over the phone. This option is great if you have questions and want real-time answers.
You will still need to provide the same basic financial information. The representative will then run a soft credit check and give you an estimate of your financing options. This method takes a little longer than the online option, but it offers a more personal touch.
Option 3: Prequalify at the Dealership
You can also start the prequalification process at your local Toyota dealer. The finance department at most dealerships can help you get prequalified on the spot. This is convenient because you can start shopping right away after getting your estimate.
However, keep in mind that some dealership finance departments may run a hard credit check even during the prequalification stage. Always ask upfront whether a soft or hard inquiry will be used. You want to protect your credit score whenever possible.
Toyota Financing Requirements
While prequalification is a low-commitment step, there are still some requirements you should be aware of. Understanding these upfront helps you know where you stand and what you might need to improve before applying.
Credit Score Expectations
Your credit score plays a big role in the financing process. Toyota Financial Services typically looks for a credit score of at least 660 for competitive rates. However, this does not mean you cannot get financed with a lower score.
Here is a general breakdown of how credit scores affect Toyota financing:
- Excellent Credit (720+): You will likely qualify for the lowest interest rates and the best terms.
- Good Credit (680-719): You should get competitive rates with favorable terms.
- Fair Credit (620-679): You can still get approved, but rates may be slightly higher.
- Below Average Credit (Below 620): Approval is still possible through special programs or co-signers.
Even if your credit score is not perfect, do not count yourself out. Toyota and its dealer network work with various lenders who cater to different credit profiles.
Income and Employment Requirements
Lenders want to see that you have a stable income. Most Toyota financing programs require a minimum monthly income, typically around $1,500 to $2,000 before taxes. You will need to provide proof of income, which can include pay stubs, tax returns, or bank statements.
Employment stability matters too. Lenders prefer borrowers who have been at the same job for at least one year. If you are self-employed, you may need to provide additional documentation, such as profit and loss statements or business tax returns.
Down Payment Expectations
A down payment is not always required, but having one strengthens your application. A typical down payment for Toyota financing ranges from 10% to 20% of the vehicle price. Putting more money down can lower your monthly payments and help you secure better interest rates.
If you are trading in a vehicle, the equity in your current car can count toward your down payment. This is where knowing your car’s value ahead of time becomes important. You can check a car’s history and get an accurate trade-in estimate before you visit the dealer.
Documentation You Will Need
Having your documents ready speeds up the process significantly. Here is what you should gather before applying:
- Valid government-issued ID
- Proof of income (pay stubs, tax returns, or bank statements)
- Proof of residence (utility bill or lease agreement)
- Insurance information
- Trade-in documentation (if applicable)
Toyota Financing Options Available
Toyota offers several financing paths to fit different budgets and lifestyles. Understanding your options helps you choose the one that makes the most sense for your situation.
Toyota Retail Loan
A standard retail loan is the most common way to finance a Toyota. You borrow a set amount and pay it back over a fixed term, usually between 36 and 72 months. The interest rate is determined by your credit profile and the term length.
Shorter terms typically come with lower interest rates but higher monthly payments. Longer terms spread out the payments, making them more affordable each month, but you may pay more in interest over the life of the loan.
Toyota Lease Options
Leasing is a popular alternative to buying. With a lease, you pay for the vehicle’s depreciation during the lease term, usually 24 to 36 months. Monthly payments are often lower than loan payments, and you get a new Toyota more frequently.
Leases come with mileage limits, typically around 10,000 to 15,000 miles per year. If you exceed those limits, you will pay extra fees at the end of the lease. Leasing works best for people who enjoy driving new vehicles and do not put excessive miles on their cars.
Toyota Special Finance Programs
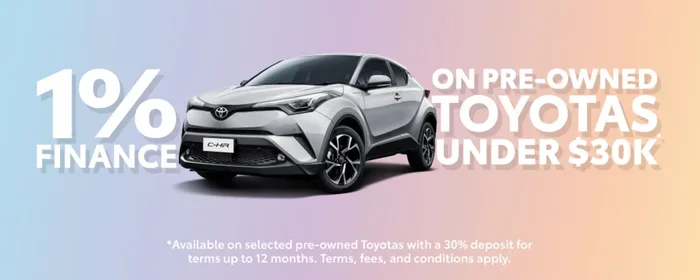
Toyota occasionally offers special financing programs with low or zero percent interest rates. These promotions are typically tied to specific models or seasonal events. They are designed to attract qualified buyers and move inventory.
Keep an eye on the Toyota website and your local dealer for current promotions. These deals can save you thousands of dollars over the life of your loan. However, they are usually reserved for buyers with strong credit profiles.
Tips to Get the Best Toyota Financing Deal
Getting prequalified is just the first step. To truly get the best deal on your Toyota financing, you need to be strategic. Here are some proven tips that can help you save money and get the terms you deserve.
Shop Around Before You Visit the Dealer
Do not settle for the first financing offer you receive. Get prequalified through Toyota Financial Services, and also check rates from your bank or credit union. Comparing offers gives you leverage at the dealership.
When you walk in with competing offers, the dealer is more motivated to match or beat them. This is one of the simplest ways to lower your interest rate and reduce your total cost.
Negotiate the Vehicle Price First
Many buyers make the mistake of focusing on the monthly payment instead of the total vehicle price. The dealer can always adjust the term or interest rate to make a high price seem affordable each month.
Instead, negotiate the out-the-door price of the vehicle first. Once you have agreed on a fair price, then discuss financing terms. This approach keeps you in control and prevents you from overpaying for the vehicle.
If you are also considering how to handle trade-ins, it helps to understand the process separately. If your current vehicle has damage, you may want to explore whether you can trade in a damaged car before heading to the dealership.
Read the Fine Print
Every financing contract has details that deserve your attention. Look for fees, penalties, and add-ons that may not have been discussed upfront. Common extras include extended warranties, gap insurance, and dealer preparation fees.
Do not be afraid to ask questions. A reputable dealer will explain every line item clearly. If something does not make sense, speak up and ask for clarification. Your comfort with the contract matters.
Consider the Total Cost, Not Just the Monthly Payment
A low monthly payment can be tempting, but it is not the whole story. A longer loan term means you pay more in interest over time. Calculate the total cost of the loan before you sign anything.
For example, a 72-month loan at 5% interest costs significantly more than a 48-month loan at the same rate, even if the monthly payment is lower. Always compare the total amount you will pay, not just what fits in your monthly budget.
Be Wary of Add-On Products
Dealers often push extra products like gap insurance, extended warranties, and paint protection. While some of these can be valuable, others are overpriced and unnecessary.
Gap insurance, for instance, can be useful if you put very little down. But if you have a solid down payment, you may not need it. Evaluate each add-on carefully and decide if it truly adds value to your purchase.
Common Mistakes to Avoid When Prequalifying for Toyota Financing
Even well-prepared buyers can stumble during the financing process. Knowing the common pitfalls helps you avoid them and stay on track to getting the best deal.
Applying for Multiple Loans at Once
Every time a lender runs a hard credit inquiry, your score takes a small hit. Applying for multiple loans within a short period can add up and damage your credit. Stick to one or two prequalification inquiries, and make sure they use soft checks.
If you do need to compare multiple offers, try to do so within a 14-day window. Credit scoring models treat multiple inquiries for the same type of loan as a single inquiry in many cases.
Overestimating What You Can Afford
Prequalification gives you an estimate, not a guarantee. Just because you are prequalified for a certain amount does not mean you should spend that much. Consider your full budget, including insurance, maintenance, fuel, and other ongoing costs.
A good rule of thumb is to keep your total car payment below 15% of your monthly take-home pay. This leaves room in your budget for everything else you need to cover.
Ignoring Your Credit Report
Before you prequalify, pull your credit report and check for errors. A single mistake, like a late payment that was actually on time, can drag your score down and cost you a higher interest rate.
You are entitled to a free credit report from each of the three major bureaus every year through AnnualCreditReport.com. Take advantage of this and fix any errors before you apply for financing.
Skipping the Preapproval Step
Some buyers stop at prequalification and skip preapproval entirely. While prequalification is helpful, preapproval carries much more weight. It shows the dealer you are a serious buyer with a lender ready to back you.
If you want maximum negotiating power, consider getting preapproved before you visit the dealership. This gives you a firm financing offer that you can use as leverage.
Not Understanding the Difference Between APR and Interest Rate
The annual percentage rate (APR) includes the interest rate plus any fees the lender charges. The interest rate alone does not reflect the true cost of the loan. Always compare APRs when evaluating different financing offers, not just the stated interest rate.
Expert Insights on Toyota Financing
Getting expert perspectives can add valuable context to your financing journey. Industry professionals consistently emphasize the importance of preparation and knowledge.
Financial advisors recommend starting the prequalification process at least two to three weeks before you plan to buy. This gives you time to compare offers, address any credit issues, and gather the necessary documentation. Rushing the process often leads to settling for less favorable terms.
Experienced car buyers also stress the value of keeping your financing and vehicle purchase as separate negotiations as possible. When the dealer handles both, it becomes harder to track whether you are getting a fair deal on the vehicle itself versus the financing. Consider arranging your own financing through a bank or credit union if the dealer’s rates are not competitive.
One final expert tip: never let a dealer tell you that you “won’t qualify” elsewhere as a reason to accept their offer. Always do your own research and trust your own prequalification results. This mindset keeps you in control and protects your financial interests.
Frequently Asked Questions About Toyota Prequalification
Does prequalifying for Toyota financing affect my credit score?
In most cases, prequalification uses a soft credit inquiry, which does not affect your credit score. However, if the dealer runs a hard inquiry during the process, it could have a small, temporary impact. Always confirm the type of credit check before you begin.
How long does Toyota prequalification last?
Toyota prequalification results are typically valid for 30 to 60 days. After that period, you may need to reapply if your financial situation has changed or if interest rates have shifted. It is best to use your prequalification estimate promptly when shopping for a vehicle.
Can I prequalify for Toyota financing with bad credit?
Yes, it is possible to prequalify even with bad credit. Toyota and its dealer network work with multiple lenders who specialize in subprime and near-prime financing. Your rates and terms may not be as favorable as those for buyers with excellent credit, but approval is still within reach. Having a co-signer can also improve your chances significantly.
Is there a cost to prequalify for Toyota financing?
No, prequalification is completely free. Toyota Financial Services and most dealerships do not charge any fees for the prequalification process. If a company asks you to pay for prequalification, that is a red flag and you should look elsewhere.
Can I prequalify online without visiting a dealership?
Absolutely. The Toyota website offers a fully online prequalification tool that you can complete from home. You will receive an estimate of your financing options without ever stepping foot on a dealer lot. This is a great way to get a head start on your car buying journey.
What is the difference between prequalification and preapproval for a Toyota loan?
Prequalification is a preliminary estimate based on the information you provide. It uses a soft credit check and gives you a general idea of your financing options. Preapproval is a more formal process that involves a hard credit check and a detailed review of your finances. Preapproval carries more weight and gives you a stronger negotiating position at the dealership.
Conclusion
Prequalifying for Toyota financing is one of the smartest things you can do before buying a Toyota. It is fast, free, and gives you a clear picture of what you can afford. Whether you choose to prequalify online, over the phone, or at the dealership, the process puts you ahead of the game.
Remember to check your credit report, gather your documents, and compare offers from multiple sources. Understanding your financing options empowers you to make confident decisions and avoid common pitfalls. The more prepared you are, the better the deal you will secure.
Take your time, ask questions, and never feel pressured to accept terms that do not feel right. Toyota financing is designed to be flexible and accessible for a wide range of buyers. With the right preparation, you can drive home in your new Toyota knowing you got the best possible deal. Start your prequalification today and take the first step toward owning the Toyota you have always wanted.