Can You Insure a Salvage Car What You Need to Know
Can you insure a salvage car? Yes, but it requires special coverage and a rebuilt title. Salvage car insurance works differently from standard auto policies, and your options depend on the vehicle’s condition and damage history. This guide walks you through everything you need to know about getting salvage car insurance and protecting your investment.
Buying a salvage car can save you a lot of money. But one question always comes up: Can You Insure a Salvage Car? The short answer is yes. But the full answer is a bit more complicated. Salvage vehicles need special insurance policies. Not every company offers them. And the coverage you get may look very different from a standard auto policy. If you are thinking about buying or already own a salvage car, you need to understand how insurance works for these vehicles.
This guide covers everything you need to know. We will walk through the types of salvage titles, how insurance works, what it costs, and tips to get the best deal. Whether you are a first-time buyer or a seasoned car enthusiast, this article will help you navigate the world of salvage car insurance with confidence.
Key Takeaways
- Salvage cars can be insured: You need a rebuilt title and a specialized policy to cover a salvage vehicle.
- Coverage is limited: Most insurers offer liability-only or agreed-value policies, not full coverage for salvage cars.
- Rebuilt title inspection is required: Your vehicle must pass a state inspection before you can register and insure it.
- Insurance costs vary: Rates depend on damage history, repairs, and the insurance company you choose.
- Common mistakes cost money: Skipping inspections or misrepresenting damage history can void your policy.
- Compare quotes: Not all insurers cover salvage vehicles, so shopping around is essential.
📑 Table of Contents
- What Is a Salvage Car and Why Does Insurance Matter?
- Can You Insure a Salvage Car? Understanding Your Options
- How Salvage Car Insurance Works in Practice
- Tips for Getting the Best Coverage for a Salvage Vehicle
- Common Mistakes People Make When Insuring Salvage Cars
- How Much Does Salvage Car Insurance Cost?
- Key Takeaways
- Conclusion
What Is a Salvage Car and Why Does Insurance Matter?
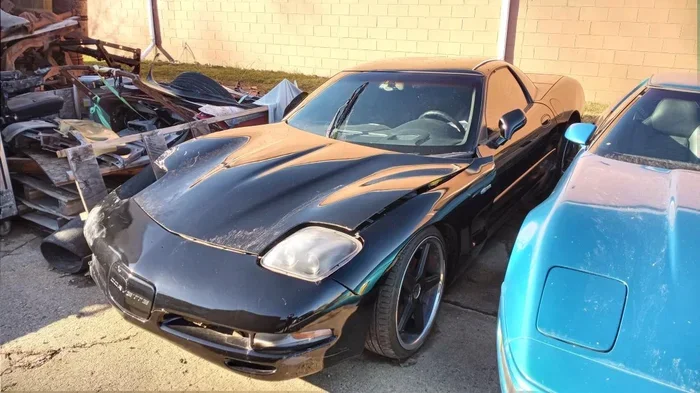
A salvage car is a vehicle that an insurance company declared a total loss. This usually happens when repair costs exceed the car’s value. The state then issues a salvage title. A salvage title means the vehicle is not roadworthy in its current state. It cannot be driven legally without repairs and a rebuilt title.
But here is the good news. Many salvage cars are fully repaired and made road-safe again. Once repaired, the owner can apply for a rebuilt title. A rebuilt title proves the car has been fixed and passed inspection. And with a rebuilt title, you can register the vehicle and get insurance.
So why does insurance matter so much? Because driving without insurance is illegal in most states. A salvage title vehicle without insurance is a risk no one should take. Plus, insurance protects you financially if something goes wrong on the road.
Types of Salvage Titles
Not all salvage titles are the same. Different states use different terms. But here are the most common types:
- Salvage title: The car was declared a total loss. It cannot be driven until repaired.
- Rebuilt title: The car was repaired and passed a state inspection.
- Non-repairable title: The car cannot be repaired or used for road travel. It may be sold for parts only.
- Flood title: The car suffered water damage, usually from flooding.
- Fire title: The car was damaged by fire.
Each title type affects your insurance options. A rebuilt title vehicle is the easiest to insure. A non-repairable title car usually cannot be insured for road use at all.
Can You Insure a Salvage Car? Understanding Your Options
The big question is Can You Insure a Salvage Car before it gets a rebuilt title? The answer is no. You cannot get a standard auto insurance policy on a car with a salvage title. The vehicle is not road legal. But once it has a rebuilt title, your options open up.
Most major insurance companies will cover a rebuilt title vehicle. However, the type of coverage you can get may be limited. Here is what you need to know about the different insurance options available for salvage cars.
Liability-Only Coverage
The most common type of coverage for salvage cars is liability-only insurance. This covers damage you cause to other people or their property. It does not cover damage to your own car. Liability coverage is required by law in most states. So this is a good starting point for anyone with a salvage title vehicle.
Liability-only policies are usually cheaper than full coverage. This makes them a popular choice for owners of rebuilt cars. But they do not protect your investment if your car gets damaged or stolen.
Comprehensive and Collision Coverage
Some insurers offer comprehensive and collision coverage for rebuilt title cars. This is closer to a standard auto policy. Comprehensive coverage pays for non-accident damage like theft or weather. Collision coverage pays for damage from accidents.
However, getting full coverage on a salvage car is harder. Many insurers limit the amount they will pay out. They may offer agreed-value coverage instead of actual cash value. This means you and the insurer agree on the car’s value upfront. If the car is totaled, you get that agreed amount.
Classic and Collector Car Insurance
If your salvage car is a classic or rare model, you might qualify for classic car insurance. Some specialty insurers cover rebuilt vehicles under collector policies. These policies often offer better rates and more flexible terms. But they usually require the car to be a preserved or restored vehicle, not a daily driver.
Non-Owner Insurance
If you do not plan to drive the salvage car regularly, non-owner insurance might be an option. This type of policy covers liability when you drive other people’s cars. It does not cover the salvage car itself. It is a budget-friendly choice for owners who are still repairing their vehicle or using it rarely.
How Salvage Car Insurance Works in Practice
Understanding the theory is one thing. But how does salvage car insurance work in real life? Let us walk through the process step by step.
Step 1: Get a Rebuilt Title
Before you can insure a salvage car, you need a rebuilt title. This means the car must be repaired and pass a state inspection. The inspection checks safety features like brakes, lights, and steering. It also checks that the frame is not bent or damaged.
Each state has different rules for rebuilt titles. Some states require a thorough inspection. Others have a simpler process. Check with your local Department of Motor Vehicles to find out what you need.
Step 2: Gather Repair Records
Insurance companies want to know what was done to the car. You should gather all repair receipts and invoices. This includes parts receipts, labor costs, and any photos of the repair work. The more documentation you have, the easier it is to get a good insurance quote.
Some insurers may also ask for a pre-purchase inspection report. If you bought the car from a seller, ask for any inspection documents you can get. This shows the insurer the car is in good condition.
Step 3: Get Insurance Quotes
Not all insurance companies cover salvage vehicles. So you may need to shop around. Start with major insurers and then check specialty companies. Some companies specialize in high-risk or non-standard auto policies. They are more likely to offer coverage for rebuilt title cars.
When you get quotes, be honest about the car’s history. Misrepresenting the damage or title status can void your policy. It is not worth the risk.
Step 4: Understand Your Policy
Once you get a policy, read it carefully. Pay attention to coverage limits, deductibles, and exclusions. Some policies may exclude certain types of damage. Others may cap the payout amount. Make sure you understand what is covered and what is not.
Step 5: Keep Your Documentation Updated
After you get your policy, keep all documents organized. Save your insurance card, policy details, and repair records in one place. If you ever need to file a claim, having everything ready makes the process much smoother.
Tips for Getting the Best Coverage for a Salvage Vehicle
Getting insurance for a salvage car does not have to be stressful. Follow these tips to get the best coverage at a fair price.
Get a Professional Inspection
Before you buy a salvage car or try to insure it, get a professional inspection. A certified mechanic can check the vehicle thoroughly. They can spot hidden problems that might affect insurance eligibility. A clean inspection report also helps you get better quotes.
Choose the Right Insurance Company
Not every insurer covers salvage vehicles. Some companies specialize in this area. Do your research and compare at least three to five quotes. Look for companies with good customer reviews and strong financial ratings.
Consider Agreed-Value Coverage
Salvage cars can be hard to value. Standard actual cash value policies may not reflect the real worth of a well-rebuilt car. Agreed-value coverage lets you set the value with the insurer. This can save you a lot of money if the car is ever totaled.
Maintain a Clean Driving Record
Your driving history affects your insurance rates. A clean record with no accidents or tickets can help you get lower premiums. Take a defensive driving course if possible. Many insurers offer discounts for safe drivers.
Bundle Your Policies
If you have other insurance policies like home or renters insurance, bundle them together. Most insurers offer multi-policy discounts. This can save you 10 to 25 percent on your premiums.
Ask About Discounts
Always ask about available discounts. Common discounts include safe driver discounts, multi-car discounts, and loyalty discounts. Some insurers also offer discounts for safety features like anti-lock brakes or airbags.
Common Mistakes People Make When Insuring Salvage Cars
Insuring a salvage car comes with its own set of challenges. Avoid these common mistakes to protect yourself and your investment.
Skipping the Rebuilt Title Process
Some people try to drive a salvage car without getting a rebuilt title. This is illegal in every state. It also means you cannot get insurance. Always complete the title transfer and inspection process before driving the car.
Misrepresenting the Vehicle’s History
Lying about a car’s damage history on an insurance application is a big mistake. If the insurer finds out, they can cancel your policy. You could also face legal consequences. Always be honest about the car’s past.
Choosing the Cheapest Policy Without Reading the Fine Print
The cheapest policy is not always the best. Some low-cost policies offer very limited coverage. They may exclude important protections. Always read the policy details before you sign.
Forgetting to Update Your Policy
If you make major repairs or changes to the car, update your insurance policy. New parts or upgrades can affect the car’s value. Your insurer needs to know about these changes to keep your coverage accurate.
Not Shopping Around
Many people just go with the first insurance company they find. But rates vary widely between insurers. Shopping around can save you hundreds of dollars a year. Take the time to compare quotes from at least three different companies.
How Much Does Salvage Car Insurance Cost?
The cost of salvage car insurance varies widely. On average, liability-only coverage for a rebuilt title car costs less than standard auto insurance. You might pay anywhere from $500 to $1,500 per year for liability coverage alone.
Full coverage policies cost more. They can range from $1,500 to $3,000 or more per year. The exact cost depends on several factors:
- The car’s make, model, and year
- The extent of the original damage
- The quality of repairs and parts used
- Your driving history and credit score
- The state you live in
- The insurance company you choose
Keep in mind that salvage cars often have lower market values. This can work in your favor when it comes to premiums. But it also means the payout may be lower if the car is ever totaled.
Comparison Table: Salvage Car vs. Standard Car Insurance Costs
| Factor | Salvage/Rebuilt Title Car | Standard Clear Title Car |
|---|---|---|
| Average Annual Premium | $500 – $3,000 | $1,000 – $2,500 |
| Coverage Options | Liability, agreed-value, limited comprehensive | Full coverage available |
| Insurer Availability | Limited, specialty companies | Most major insurers |
| Required Inspection | Yes, rebuilt title inspection | Usually not required |
| Total Loss Payout | Agreed value or actual cash value | Actual cash value |
| Deductible Range | $500 – $2,000 | $250 – $1,000 |
As you can see, insuring a salvage car costs less in many cases. But the coverage options are more limited. It is important to weigh the cost savings against the coverage you actually need.
Key Takeaways
- Salvage cars can be insured: You need a rebuilt title and a specialized policy to cover a salvage vehicle.
- Coverage is limited: Most insurers offer liability-only or agreed-value policies, not full coverage for salvage cars.
- Rebuilt title inspection is required: Your vehicle must pass a state inspection before you can register and insure it.
- Insurance costs vary: Rates depend on damage history, repairs, and the insurance company you choose.
- Common mistakes cost money: Skipping inspections or misrepresenting damage history can void your policy.
- Compare quotes: Not all insurers cover salvage vehicles, so shopping around is essential.
Conclusion
The answer to Can You Insure a Salvage Car is yes, with the right approach. A salvage car with a rebuilt title can be insured through liability-only or agreed-value policies. The key is to complete the title process, gather your repair records, and compare quotes from multiple insurers.
Insurance for a salvage vehicle may cost less than standard auto insurance. But it also comes with limitations. You may not get the same level of coverage as a clear-title car. That is why it is so important to read your policy carefully and understand what is covered.
Take your time. Do your research. And never be afraid to ask questions. A good insurance agent can help you find the right policy for your salvage car. The goal is to protect yourself, your investment, and your peace of mind on the road.
With the right coverage in place, you can enjoy your rebuilt vehicle with confidence. Just remember to keep your documentation updated and your policy current. A little effort goes a long way when it comes to salvage car insurance.
Frequently Asked Questions
Can you insure a salvage car without a rebuilt title?
No, you cannot insure a salvage car without a rebuilt title. The vehicle must be repaired, pass a state inspection, and receive a rebuilt title before any insurance company will cover it. Driving a salvage title car on public roads without insurance is illegal in every state.
What type of insurance coverage is available for salvage cars?
Most salvage cars qualify for liability-only or agreed-value insurance policies. Some insurers also offer comprehensive and collision coverage for rebuilt title vehicles. The availability of coverage depends on the insurance company and the condition of the vehicle.
How much does it cost to insure a salvage car?
Insurance costs for salvage cars vary widely. Liability-only coverage typically costs between $500 and $1,500 per year. Full coverage policies can range from $1,500 to $3,000 or more annually. Your rates depend on factors like the car’s value, your driving history, and your state of residence.
Will my salvage car insurance cover a total loss?
If you have agreed-value coverage, the insurer pays the pre-agreed amount if the car is totaled. With actual cash value policies, the payout is based on the car’s market value at the time of loss. Salvage cars often have lower values, so the payout may be less than a standard vehicle.
Can I get full coverage insurance for a salvage car?
Some insurers offer full coverage for rebuilt title cars, but options are limited. Many companies cap the coverage or offer agreed-value policies instead. It is important to shop around and find an insurer that specializes in salvage or high-risk vehicle coverage.
What documents do I need to insure a salvage car?
You will need a rebuilt title, repair receipts, inspection reports, and photos of the vehicle. Some insurers also ask for a pre-purchase inspection report or proof of professional repairs. Having all documentation ready speeds up the insurance application process significantly.